An accident claim lawyer is an attorney who recovers money when someone else’s carelessness injures you. You should hire one when injuries are serious, fault is disputed, or the insurer offers too little. Most work on contingency, so you pay nothing upfront and the fee comes out of your payout. A crash can flip your life in a single afternoon. Bills arrive fast, and insurance adjusters call even faster. This guide covers what these lawyers do, what they cost, and how claims move. It also shows you how to choose well.
What an Accident Claim Lawyer Actually Does
Think of this lawyer as your investigator, negotiator, and trial advocate in one person. The work starts long before any lawsuit exists. Most of it ends without a courtroom. A good lawyer also takes the weight off your shoulders. You focus on healing while they handle the paperwork, the deadlines, and the pressure from insurers.
They Build the Evidence Early
Proof fades quickly after an accident. Skid marks wash away, cameras overwrite footage, and witnesses forget details. A lawyer moves fast to lock down the facts. Typical evidence work includes:
- Police and incident reports: Your lawyer requests the official record and checks it for errors.
- Scene documentation: They photograph the location, measure sight lines, and note hazards such as broken lighting.
- Witness statements: They interview people while memories stay fresh.
- Video and data: They send preservation letters so businesses keep footage and vehicle data.
- Expert opinions: They hire reconstruction specialists, doctors, and economists when the case needs them. Preservation letters matter more than most people realize. A trucking company, for example, may delete driver logs on a routine schedule. A prompt letter stops that.
They Prove Who Caused the Accident
Every injury claim rests on fault. Your lawyer must show that another party owed you a duty of care and broke it. They must also show that the breach caused your injuries. This is where many claims stall. Insurers often argue that you share the blame or that your injuries pre-existed the crash. A lawyer answers those arguments with records, expert opinions, and clear timelines. Fault rules also differ by state. Some states bar your claim if you carry more than half the blame. Others reduce your payout by your percentage of fault. Your lawyer knows which rule applies and shapes the case around it.
They Document Your Full Losses
Many people count only the hospital bill. A lawyer counts everything. That includes losses you have not yet felt. Here is what a thorough lawyer tracks:
- Medical care: Emergency treatment, surgery, therapy, medication, and future procedures.
- Lost income: Missed shifts, reduced hours, and lost earning power over time.
- Out-of-pocket costs: Rental cars, home help, travel to appointments, and medical devices.
- Pain and suffering: Physical pain, anxiety, sleep loss, and damage to daily life.
- Property damage: Vehicle repair or replacement and personal items. Your lawyer gathers records for each category. They also work with your doctors to explain how the injury will affect your future.
They Negotiate With Insurance Companies
Insurers employ professionals who settle claims for a living. They know the formulas, the tactics, and the language that protects their profit. You face that team alone unless you hire help. Your lawyer takes over every call and letter. They send a demand package with your evidence and a specific number. Then they negotiate, push back on lowball offers, and recommend whether to accept. Importantly, the lawyer does not decide for you. You hold the final say on any settlement. Your lawyer’s job is to give you the facts and an honest opinion.
They Take the Case to Court When Needed
Most claims settle. Some do not. When the insurer refuses a fair deal, your lawyer files a lawsuit. The case then enters litigation. Litigation adds several stages. These include written questions, document exchanges, sworn depositions, and sometimes mediation. A small share of cases reach a full trial. The mere readiness to try a case changes negotiations. Insurers pay more when they know your lawyer can win in front of a jury.
Types of Accident Cases an Accident Claim Lawyer Handles
Personal injury lawyers handle a wide range of cases. Many focus on one or two areas. Matching your case type to a lawyer’s experience improves your odds. Each case type brings its own rules, insurers, and evidence. A trucking crash looks nothing like a grocery store fall. The sections below show the main categories.
Car Accidents
Car crashes make up the largest share of injury claims. Rear-end collisions, intersection crashes, and distracted driving cases lead the list. Fault disputes show up often. Insurance also complicates these cases. You may deal with your own insurer, the other driver’s insurer, or both. Some states use no-fault rules, which change who pays first.
Truck and Commercial Vehicle Accidents
Large trucks cause severe injuries because of their weight and size. These cases involve more parties than a typical crash. The driver, the carrier, the vehicle owner, and a cargo loader may all share blame. Federal safety rules also apply to commercial drivers. They cover hours of service, maintenance, and driver qualifications. A lawyer who knows these rules can find violations that others miss.
Motorcycle Accidents
Riders face higher injury risks and stronger bias. Some jurors and adjusters assume that riders cause their own crashes. A skilled lawyer counters that bias with facts. Typical motorcycle claims involve drivers who miss riders, turn left unsafely, or open car doors. Road defects can also cause these wrecks.
Pedestrian and Bicycle Accidents
Pedestrians and cyclists have no protective frame. Even low-speed impacts can cause lasting harm. Hit-and-run cases appear often in this category. Your own auto policy may still help. Uninsured motorist coverage can pay when the driver flees or carries no insurance. A lawyer checks every policy that might apply.
Slip and Fall Accidents
Property owners must keep their premises reasonably safe. When wet floors, broken stairs, or poor lighting injure a visitor, the owner may owe compensation. These cases are called premises liability claims. Proof is the main challenge. You must show that the owner knew or should have known about the hazard. Fast evidence gathering makes a big difference here.
Rideshare Accidents
Rides booked through an app create layered insurance coverage. Coverage depends on the driver’s status. They may be waiting, heading to a pickup, or carrying a passenger. Insurers often dispute which phase applied. A lawyer sorts out these layers. They also obtain app data that shows what the driver was doing during the crash.
Workplace Accidents
Most employees injured at work receive workers’ compensation. That system pays medical bills and part of lost wages regardless of fault. It also limits your right to sue your employer. Still, you may have a separate claim against a third party. A defective machine maker or a negligent subcontractor can face a lawsuit. A lawyer can spot those options.
Product Defect and Other Injury Cases
Defective products can injure consumers through poor design, bad manufacturing, or missing warnings. Dog bites, nursing home neglect, and construction site falls also fall under injury law. Each requires special knowledge. When you search for help, ask about experience with your exact situation. General skill matters, but specific experience wins cases.
When You Need an Accident Claim Lawyer and When You Can Go Alone
Not every accident requires an attorney. Some claims are small and simple. Others carry high stakes that justify professional help. Questions like “do I need a lawyer after a car accident” deserve a clear, honest answer. The right choice depends on your injuries, the fault dispute, and the insurer’s behavior.
Situations Where You Should Hire a Lawyer
Hire a lawyer promptly when any of these apply:
- Serious injuries: Broken bones, head trauma, spinal injuries, burns, or anything needing surgery.
- Ongoing treatment: Injuries that need weeks or months of care, or lasting limits on work.
- Disputed fault: The other side blames you, or the facts remain unclear.
- Multiple parties: Several drivers, companies, or insurers share responsibility.
- Low or slow offers: The insurer offers little, delays, or stops returning calls.
- Wrongful death: A family member died because of someone else’s actions.
- Uninsured or underinsured drivers: Collecting becomes harder and requires policy knowledge.
- Denied claims: The insurer rejected your claim or accused you of fraud. Each of these situations raises the stakes. A single mistake can cost you thousands of dollars. Early advice prevents most of those mistakes.
Situations Where You May Not Need One
Some cases truly stay simple. A minor fender bender with no injuries and clear fault often resolves through insurance alone. You file a property damage claim, repair the car, and move on. You might also skip a lawyer if you only had a minor bruise that healed in days. In that case, legal fees may not match the claim’s size. Even then, a free consultation costs nothing and gives peace of mind.
A Quick Self-Check
Ask yourself these questions before you decide:
- Did a doctor treat me beyond a single visit?
- Did I miss work because of my injury?
- Does the other side deny fault?
- Did the insurer ask for a recorded statement or medical records?
- Do I feel unsure about what my claim is worth? If you answered yes to any one, speak with a lawyer. The consultation is usually free. You lose nothing by asking.
The Hidden Risk of Waiting
Delay hurts claims in quiet ways. Evidence disappears, deadlines approach, and insurers gain time to build their story. Gaps in medical treatment also give adjusters a reason to doubt your injuries. Therefore, the best moment to call a lawyer is soon after you receive medical care. You do not need to wait until the insurer causes trouble.
What an Accident Claim Lawyer Costs
Cost worries stop many injured people from calling a lawyer. That fear usually has no basis. Nearly all personal injury lawyers use a contingency fee. They get paid only if you win. Understanding accident lawyer fees helps you compare offers and avoid surprises. The details live in your fee agreement, so read it carefully.
How Contingency Fees Work
Under this arrangement, you pay no hourly rate and no retainer. Your lawyer takes a percentage of the money recovered. If you recover nothing, you typically owe no attorney fee. This model aligns interests. Your lawyer earns more when you earn more. They also have a strong reason to avoid weak, slow cases.
Typical Percentages
Fee rates vary by lawyer, state, and case stage. Many firms charge around one third of the recovery when the case settles before a lawsuit. The rate often rises to about forty percent once the firm files suit. Some states cap fees in certain case types. Medical malpractice and claims against government bodies often face limits. Your lawyer should explain which limits apply to you.
Fees Versus Case Costs
Many people confuse these two items. The attorney fee pays for the lawyer’s time and skill. Case costs cover expenses needed to build the claim. Common case costs include:
- Filing fees: Charges the court collects when your lawyer files a lawsuit.
- Medical records: Fees that hospitals and clinics charge for copies.
- Expert witnesses: Specialists who review evidence and testify.
- Depositions: Court reporter and transcript charges.
- Investigators and travel: Costs for scene visits and witness interviews. Ask how your firm handles these costs. Some deduct them from your share after the fee. Others deduct them before calculating the fee. The order changes your final payout.
A Simple Payout Example
Suppose your case settles for $90,000. The firm charges a one-third fee, which equals $30,000. Case costs total $3,000. If the firm calculates the fee on the gross amount, you owe $30,000 plus $3,000. Your net recovery is $57,000 before any medical liens. Your lawyer should also negotiate liens down, which raises your final amount.
Medical Liens and Repayments
Health insurers, hospitals, and government programs often claim a share of your settlement. They call this a lien or reimbursement right. Ignoring them can create serious trouble later. A strong lawyer negotiates these claims. Reductions are common, and they can add thousands to your take-home amount. Ask whether the firm handles lien negotiation at no extra charge.
Questions to Ask About Fees
Request clear answers before you sign anything:
- What percentage do you charge at each stage?
- Do you calculate the fee before or after costs?
- Who advances case costs, and what happens if we lose?
- Do I owe anything if the case ends without a recovery?
- Will you negotiate medical liens, and is that included? Get the agreement in writing. A trustworthy lawyer welcomes these questions and answers without hesitation.
What to Do After an Accident to Protect Your Claim
Your actions in the first hours and days shape the whole claim. Fear and adrenaline make clear thinking hard. A simple plan helps. Knowing what to do after an accident protects both your health and your legal rights. The steps below follow the order that matters most.
Step 1: Get to Safety and Call for Help
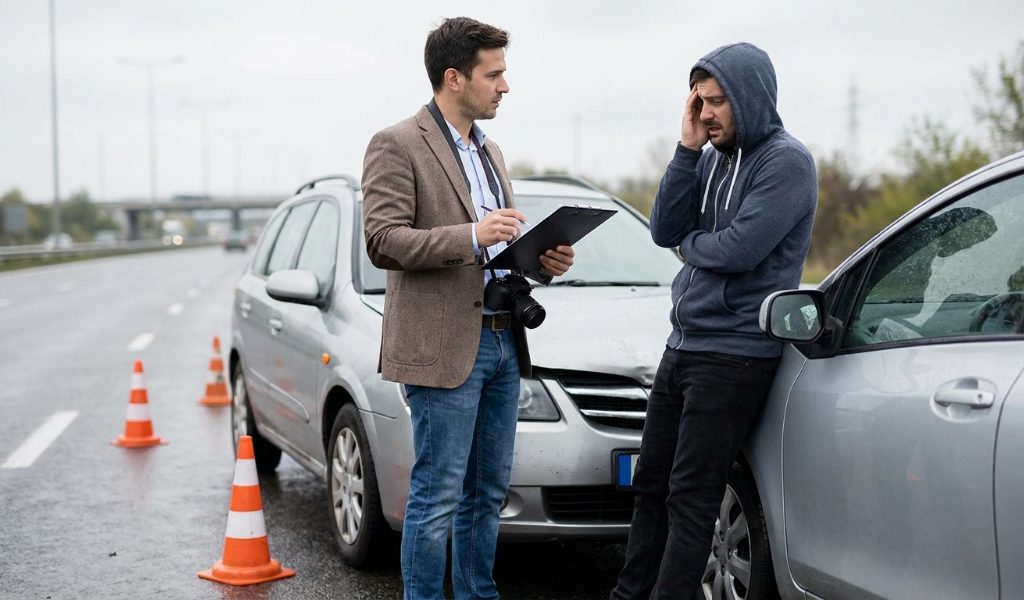
Move out of traffic if you can do so safely. Turn on hazard lights and stay away from moving cars. Call emergency services and report any injuries. Always request police at the scene. An official report carries weight with insurers. It also records the time, place, and parties involved.
Step 2: Get Medical Care Right Away
Seek care the same day, even if you feel fine. Adrenaline hides pain, and injuries like concussions and internal bleeding can appear later. Medical records also create the link between the accident and your injuries. Follow your doctor’s advice exactly. Attend every appointment and take every prescribed treatment. Gaps in care give insurers an easy argument against you.
Step 3: Collect Evidence at the Scene
If you can, gather proof while the scene remains fresh. Your phone makes this simple. Focus on these items:
- Photos: Capture vehicles, damage, road conditions, signs, signals, and your visible injuries.
- Contact details: Get names, phone numbers, license plates, and insurance information.
- Witnesses: Ask bystanders for their names and numbers.
- Notes: Write down what happened while you still remember it clearly. Take more photos than you think you need. You can delete extras later, but you cannot retake a scene.
Step 4: Watch What You Say
Stay polite, but keep your statements simple. Never guess about fault or speed. Do not say “I’m sorry” in a way that sounds like an admission. Stick to the facts you know for certain. Let the police and insurers sort out blame. Your lawyer will handle the rest.
Step 5: Report the Accident and Keep Records
Notify your own insurer promptly. Most policies require timely notice. Provide basic facts, but decline to give a long recorded statement before you speak with a lawyer. Start a folder for everything related to the accident. Keep bills, receipts, letters, photos, and a pain journal. Record missed work, daily limits, and emotional struggles.
Step 6: Stay Off Social Media
Insurers search public profiles. A single photo of you at a party can undermine your injury claim. Even innocent posts can look bad out of context. Therefore, pause your posting until the claim ends. Tighten your privacy settings, but do not delete old posts. Deleting content can look like hiding evidence.
Step 7: Talk to a Lawyer Early
A free consultation costs nothing and often reveals mistakes you can still fix. The sooner your lawyer joins, the more evidence they can save. Early help also stops harmful insurer contact. Bring any documents you have. Even a rough set of notes gives the lawyer a head start.
How an Accident Claim Moves From Start to Payout
Many clients ask one question first: how long will this take? The honest answer is that it depends. Simple claims can finish in a few months. Complex cases can take years. Understanding how long an accident claim takes requires looking at each phase. The stages below show what happens and why delays occur.
Phase 1: Free Consultation and Hiring
You meet the lawyer, explain what happened, and share your records. The lawyer reviews the case and explains your options. If both sides agree, you sign a fee agreement. This phase often takes days. Your lawyer then sends notice to all insurers and takes over communication.
Phase 2: Investigation and Treatment
Your lawyer gathers evidence while you receive medical care. They avoid settling too early because your full injuries may not be clear. This phase often takes the longest. Most lawyers wait until you reach maximum medical improvement. That means your doctor believes your condition has stabilized. Settling sooner risks leaving future costs uncovered.
Phase 3: The Demand Letter
Once treatment ends, your lawyer prepares a demand package. It includes medical records, bills, wage proof, photos, and a legal argument. It also states the amount you seek. The insurer usually has thirty days or more to respond. Expect a first offer far below the demand. That is normal and part of the process.
Phase 4: Negotiation
Offers and counteroffers go back and forth. Your lawyer explains the strengths and weaknesses of each proposal. You decide whether to accept. Many claims settle in this stage. The process can last weeks or months depending on the insurer’s attitude and the case’s complexity.
Phase 5: Filing a Lawsuit
If negotiations fail, your lawyer files a complaint in court. Filing does not mean you will go to trial. It often pushes the insurer to take the case seriously. Lawsuits add time. The discovery phase alone can last six months to a year.
Phase 6: Discovery, Mediation, and Trial
Both sides exchange documents and take sworn statements. Many courts then require mediation, where a neutral person helps the parties find a deal. Most cases settle here or before. If mediation fails, the case goes to trial. Trial dates depend on court calendars and may sit a year or more away.
What Speeds Up or Slows Down a Claim
Several factors control the pace:
- Injury severity: Serious injuries need longer treatment and more documentation.
- Fault disputes: Disagreements about blame lead to more investigation and more arguments.
- Insurance limits: Cases that exceed policy limits require extra steps.
- Court backlog: Busy courts delay hearings and trials.
- Your records: Missing bills or treatment gaps slow everything down. Patience pays off. Rushed settlements often leave money on the table.
Settlement Payment Timing
Once you accept an offer, you sign a release. The insurer then issues payment, often within a few weeks. Your lawyer deposits the funds in a trust account. Next, the firm pays any liens, case costs, and fees. You receive the remaining balance. This final step usually takes a few additional weeks.
What Your Accident Claim Can Be Worth
Everyone wants a number early. Unfortunately, no honest lawyer can give an exact figure on day one. Claim value depends on facts that unfold over time. Understanding accident claim value helps you set realistic expectations. It also helps you spot an offer that falls short.
Economic Damages
Economic damages cover losses you can add up with receipts and records. They form the foundation of your claim. Insurers generally accept these numbers more easily. They include:
- Past and future medical bills: Hospital stays, surgery, therapy, medication, and long-term care.
- Lost wages: Pay you missed while you recovered.
- Lost earning capacity: Reduced ability to earn money in the future.
- Property damage: Repair or replacement costs.
- Other expenses: Home modifications, childcare, and transportation.
Non-Economic Damages
These losses lack receipts but still hurt. They reflect how the injury changes your life. Courts and insurers call them pain and suffering. Examples include:
- Physical pain: Both current and expected future pain.
- Emotional distress: Anxiety, depression, fear, and trauma.
- Loss of enjoyment: The inability to play sports, travel, or enjoy hobbies.
- Disfigurement: Scarring or visible changes.
- Relationship strain: Effects on your family and marriage.
How Insurers Estimate Pain and Suffering
Insurers often use a multiplier method. They multiply your medical bills by a number, commonly between one and five. Serious, permanent injuries earn higher multipliers. Some insurers also use software that scores claims. Your lawyer knows these systems and argues against unfair scoring. Strong documentation drives the biggest gains.
Factors That Raise or Lower Value
Many details move the number:
- Injury type: Permanent and life-changing injuries command higher value.
- Treatment record: Consistent care strengthens your story.
- Your fault share: A shared blame percentage reduces your payout in many states.
- Policy limits: The at-fault party’s coverage often caps what you can collect.
- Your age and job: These affect future earnings and life expectancy calculations.
- Venue: Some courts and juries tend to award more than others.
A Worked Example
Imagine a driver rear-ends you. Your medical bills total $25,000, and you lose $8,000 in wages. A reasonable estimate for pain and suffering might reach $50,000 based on your recovery. That brings the claim to $83,000. Suppose a court finds you ten percent at fault under shared-blame rules. Your recovery then drops by $8,300. This shows why fault arguments matter so much.
Punitive Damages
Rarely, courts add punitive damages. These punish extreme misconduct such as drunk driving. They do not apply to ordinary negligence. Most claims never reach this level. Still, a lawyer can tell you whether your facts might qualify.
Dealing With Insurance Companies After an Accident
Insurance adjusters sound friendly. They ask about your health and sympathize with your pain. Meanwhile, they search for ways to reduce what they pay. Handling an insurance adjuster after an accident carefully protects your claim. A few common mistakes can cost you dearly.
Recorded Statements
The other driver’s insurer will likely ask for a recorded statement. You have no duty to give one. Adjusters use these recordings to find small inconsistencies. Politely decline until you speak with a lawyer. You can say, “I’m not ready to give a statement.” That response is firm and safe.
Early Settlement Offers
Quick offers sound tempting. They arrive before you know your full injuries. Once you accept, you usually cannot reopen the claim. Never accept a first offer without review. Early money often equals a fraction of fair value.
Medical Record Releases
Insurers may ask you to sign a broad release for all your medical history. That lets them hunt for old problems to blame. It also exposes private information. Offer only the records that relate to your accident injuries. Your lawyer can negotiate the scope.
Admitting Fault or Minimizing Injuries
Casual phrases hurt claims. “I’m fine” or “It was my fault” can appear in an adjuster’s notes forever. Even polite habits can backfire. Describe your symptoms honestly and accurately. Avoid guessing or downplaying. Stick to the facts.
Your Own Insurance Company
Your own insurer is not always on your side. Although you pay premiums, it still wants to limit payments. Collision, medical payments, and uninsured motorist claims all involve real negotiation. Report the accident promptly and cooperate on required steps. However, speak with a lawyer before giving detailed statements.
Bad Faith Behavior
Some insurers delay, deny without reason, or ignore policy duties. Many states treat this as bad faith. It can expose the insurer to extra liability. Keep records of all communication. Your lawyer can use that record to hold the insurer accountable.
Accident Claim Time Limits You Cannot Miss
Every state sets a deadline for filing an injury lawsuit. Courts enforce these deadlines strictly. Miss yours, and you almost certainly lose your right to compensation. The accident claim statute of limitations varies widely by state and case type. Learning your deadline early protects your options.
Typical Deadlines
Most states give between one and six years for injury lawsuits. Two to three years is the most common range. Wrongful death deadlines often differ. Because rules vary, never rely on a general number. A lawyer can confirm the exact date for your situation.
Shorter Deadlines for Government Claims
Claims against cities, counties, states, or public agencies often follow special rules. You may need to file a formal notice within weeks or months. Missing that notice can end your claim. For example, a pothole injury or a public bus crash may trigger these rules. Contact a lawyer immediately in these cases.
Exceptions That May Extend a Deadline
Certain situations pause or extend the clock. Examples include:
- Minors: Many states delay the clock until the injured child turns eighteen.
- Delayed discovery: The clock may start when you reasonably learn of the injury.
- Incapacity: Serious mental or physical incapacity can extend the time.
- Defendant absence: Some states pause the clock if the at-fault party leaves the state. Do not rely on these exceptions. They apply narrowly, and courts review them closely.
Why Waiting Hurts Even Before the Deadline
A deadline is only the outer limit. Evidence weakens long before that date. Witnesses move, and records vanish. Moreover, insurers know when your clock runs out. They may stall until time almost expires, then offer little.
How to Choose the Right Accident Claim Lawyer
Not all lawyers deliver the same results. Skill, focus, and communication vary widely. A careful search protects your claim and your peace of mind. Treat the first meeting as a two-way interview. You judge the lawyer as much as they judge your case.
Look for Relevant Experience
Start with focus. A lawyer who handles injury claims every week knows the tactics, the judges, and the insurers. A lawyer who dabbles in many fields may not. Ask about cases similar to yours. For example, if a truck hit you, ask how many trucking cases they have handled. Specific answers beat general promises.
Check Credentials and Standing
Verify that the lawyer holds an active license in your state. Your state bar association lists discipline records. Look for any serious complaints. Also review their trial history. Lawyers who try cases earn more respect from insurers. That reputation can raise settlement offers.
Read Reviews With a Critical Eye
Online reviews help, but read them carefully. Look for patterns rather than single stories. Consistent praise for communication and honesty matters more than a perfect score. Check multiple platforms. Peer ratings and local referrals add useful context. Friends and family can also share honest experiences.
Test Communication Early
Pay attention to how the firm treats you from the first call. Do they return calls quickly? Do they explain things in plain language? Poor communication is the top complaint against law firms. If you feel ignored during the consultation, expect the same later.
Understand Who Will Actually Work on Your Case
Some large firms assign cases to junior staff after the sales meeting. Ask who will handle your claim day to day. Ask how often you will receive updates. You deserve to know the lawyer’s caseload too. An overloaded lawyer cannot give your case enough attention.
Compare Resources
Complex cases need money and staff. Experts, investigators, and trial preparation cost real funds. Ask whether the firm can advance those costs. A small firm can still do excellent work. Just confirm that it has the capacity your case needs.
Questions to Ask at the Consultation
Bring a short list:
- How many cases like mine have you handled?
- Who will work on my case, and how can I reach them?
- How do you charge, and what costs might I face?
- What is your honest view of my claim’s strengths and risks?
- How long do you expect this process to take?
- Would you be willing to take my case to trial? Listen to how the lawyer answers. Clear, direct responses show confidence and honesty.
Red Flags That Should Make You Walk Away
Most lawyers act ethically. Still, a few warning signs deserve attention. Trust your instincts when something feels wrong. Watch for these red flags:
- Guaranteed results: No honest lawyer can promise a specific outcome or amount.
- Pressure to sign: Good lawyers give you time to decide.
- Unsolicited contact: Lawyers who chase you at the hospital may violate ethics rules.
- Vague fee terms: Unclear or verbal-only fee agreements invite trouble.
- Upfront fees for injury cases: Contingency work rarely needs a retainer.
- Poor communication: Missed calls and slow replies tend to continue.
- Settlement mill reputation: Some firms rush clients into quick, cheap settlements. If you spot any of these, keep looking. Plenty of qualified lawyers will welcome your case.
How to Help Your Lawyer Win Your Case
Your lawyer carries the legal work, but your actions still matter. Cooperation can raise your settlement. Mistakes can lower it. A few habits make the biggest difference.
Keep Treating and Keep Records
Follow your treatment plan. Tell your doctors about all symptoms, even small ones. Honest and complete medical notes strengthen your case. Also save every bill and receipt. Update your pain journal weekly.
Answer Quickly and Honestly
Respond to your lawyer’s requests as soon as you can. Delays slow the case. Always tell the full truth, even about facts that seem harmful. Surprises hurt more than bad facts. Your lawyer can plan for a problem they know about.
Avoid Discussing the Case
Do not talk about your claim with anyone except your lawyer and doctors. That includes friends, coworkers, and online groups. Insurers can obtain these conversations. Direct any insurer calls to your lawyer. A short, polite referral is enough.
Stay Realistic
Claims take time, and results rarely match your first hopes. Trust the process and keep communication open. Ask questions whenever you feel unsure. Your lawyer can explain every step. A strong partnership improves the experience and often the outcome.
Final Thoughts: Take the First Step Before Mistakes Pile Up
An accident claim lawyer protects your health, finances, and future when someone else causes harm. They gather proof, fight insurers, and push for a fair result. The right lawyer also lifts stress from your daily life. Do not wait for the insurer to decide your case for you. Evidence fades, deadlines approach, and early missteps cost real money. A short call today can save you months of trouble. Write down what happened and gather your records. Then schedule a free consultation with a qualified local injury lawyer. Compare at least two firms before you decide. Take action now so your recovery can come first.
Frequently Asked Questions
How much does an accident claim lawyer cost?
Most charge a contingency fee of about one third to forty percent, with nothing owed upfront.
How long does it take to settle an accident claim?
Simple claims can settle in months, while complex or disputed cases may take one to three years.
Can I handle an accident claim without a lawyer?
You can for minor, no-injury accidents, but serious injuries or disputed fault call for professional help.
What if I was partly at fault for the accident?
Many states still let you recover money, but your payout drops by your percentage of fault.
How soon should I contact a lawyer after an accident?
Contact one as soon as you receive medical care, ideally within days, before you talk to insurers.